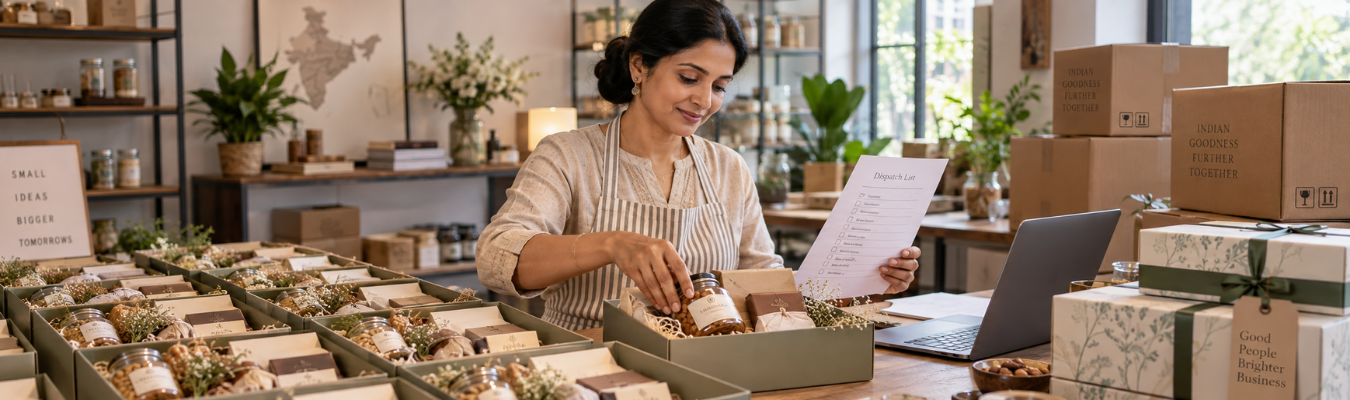
An order for 20 hampers and an enquiry for 500 hampers may contain the same products. They are not the same business problem. At 20 units, a founder can often manage customization personally, buy packaging in small quantities, collect payment before dispatch and fix a last-minute mistake herself.
At 500 units, one missing label can become 500 missing labels. A ₹30 packaging miscalculation becomes ₹15,000. A buyer paying 30 days after delivery can leave the founder funding raw materials, labor and logistics for weeks. That is why getting “corporate ready” is less about looking corporate and more about building a business that can accept a larger order without damaging its margins or reputation.
For women-led product brands in particular, this is becoming a practical growth path. But, the opportunity comes after the preparation.
First question: can the business quote the order properly?
Retail pricing is a poor starting point for many B2B quotes. Before sending a corporate rate, calculate the true order cost:
Product cost + customization + corporate packaging + wastage + labor + outer cartons + logistics + payment cost + applicable tax + margin
If a ₹600 retail product is offered to a company at ₹450 merely because the order is large, the discount may disappear once customized sleeves, individual name cards, master cartons and delivery to three locations are added. Bulk pricing should come from a different cost structure—not from choosing an attractive discount percentage.
Does a business need GST to take corporate orders?
Not automatically. GST registration is determined by the applicable GST rules, including turnover, supply type, location and other compulsory-registration provisions—not simply by the fact that the customer is a company.
However, corporate procurement policy and GST law are two different questions. A corporate buyer may prefer or require GST-registered vendors as part of its onboarding or tax processes even where the seller would not otherwise be legally required to register.
If the business is not GST registered, it should not charge GST as though it were. The CGST Act prohibits an unregistered person from collecting an amount as tax under the Act. If registered, the invoice needs to follow GST requirements. CBIC's invoice rules include details such as supplier and recipient GSTIN where applicable, invoice number and date, HSN/SAC, description, taxable value, tax rate and amount, and place of supply for interstate transactions. Women Listed's existing GST guide makes the same important distinction: a corporate customer's request for an invoice can trigger the conversation, but the correct GST position still depends on how the business operates.
Before quoting a corporate buyer, know:
- whether you are GST registered;
- the applicable GST rate and classification;
- whether your quote is tax-inclusive or tax-exclusive;
- the buyer's legal name, billing address and GSTIN;
- where the goods will be delivered; and
- which documents their accounts team requires.
Clarify this before the purchase order, not while raising the final invoice.
Set an MOQ you can explain
MOQ—minimum order quantity—should not be a number invented because “bulk buyers expect one.” It should come from the economics of the order. A custom printed box may require a vendor minimum of 250. A screen-printed pouch may become economical only at 100. A baker may need batches of 24 for a particular product. A packaging supplier may sell master cartons in fixed case quantities. Those constraints should shape the MOQ.
A useful corporate rate card can therefore have layers:
Standard bulk order: existing product and packaging
Customized order: higher MOQ or customization charge
Sample/prototype: paid sample or small approval batch
Large-volume tier: revised rate once production efficiencies genuinely improve
This is much easier to defend than giving different prices depending on how confident the founder feels during each call.
Packaging has to survive procurement, not only Instagram
Retail packaging is often designed around the moment the customer opens it. Corporate packaging has to survive everything that happens before that moment.
Ask:
- Will 100 units stack safely?
- What is the weight of a master carton?
- Can glass break during interstate transport?
- Will chocolate, candles or food products tolerate the delivery conditions?
- Does every unit need a client logo or employee name?
- Are barcodes, SKUs or purchase-order references required?
- Can the outer carton be counted quickly at the client's receiving desk?
- Are food labels fully compliant?
- What happens if five pieces arrive damaged?
Women Listed's earlier D2C editorial work captures this shift well: corporate buyers need more than attractive products; they need pricing, minimum quantities, lead times, invoicing, quality control and dependable fulfillment. That is the difference between gift-worthy and procurement-ready.
Build a vendor-onboarding folder before anyone asks for it
Corporate buyers differ, but small businesses can save days by keeping frequently requested information organized in one folder. Depending on the business, this may include:
- PAN and legal/entity information;
- GST registration certificate, where applicable;
- Udyam certificate, if registered;
- cancelled cheque or bank verification;
- business address;
- FSSAI or other sector licences;
- product catalogue and specifications;
- quotation template;
- bank and payment details;
- relevant test certificates or declarations; and
- one contact responsible for the order.
Do not send every document with the first enquiry. The goal is simply to be ready when procurement starts onboarding.
Never start a large customized order on a verbal “yes”
For a routine retail purchase, a WhatsApp confirmation may be workable. For a corporate order involving customization, production commitments and significant raw-material spend, insist on a clear written commercial document—usually the buyer's purchase order or other formally accepted terms.
Check:
- exact SKU and quantity;
- agreed price;
- GST treatment;
- artwork and customization;
- delivery deadline;
- payment terms;
- cancellation terms;
- rejection or replacement conditions; and
- who has authority to approve changes.
A purchase order that says “500 hampers” is not enough if nobody has agreed whether each one includes a printed sleeve, note card and individual name label.
Credit terms can turn a profitable order into a cash-flow problem
Suppose a founder receives a ₹4 lakh corporate order. Production requires ₹2 lakh in materials and packaging before dispatch. The buyer will pay 30 or 45 days after an accepted invoice. The business therefore has a working-capital requirement, even if the order is profitable on paper.
Before accepting the job, map:
Advance received → supplier payments → production → dispatch → invoice acceptance → payment due date
For customized or material-heavy orders, founders may negotiate an advance or milestone structure where the buyer's procurement policy allows it. For established corporate credit, know exactly what starts the clock. Is payment counted from invoice date, goods-receipt confirmation, acceptance in a vendor portal or another approved milestone? Women Listed's financial planning guide for entrepreneurs explains why a healthy sales figure can still create pressure when collections arrive later than expenses.
Udyam-registered micro and small suppliers should understand the 45-day rule
For qualifying micro and small enterprises, Section 15 of the MSMED Act provides that a written payment period agreed between supplier and buyer cannot exceed 45 days from acceptance or deemed acceptance. A valid Udyam-registered micro or small enterprise may also use the MSME Samadhaan route for qualifying delayed-payment disputes.
That does not remove the need for disciplined collections. Send accurate invoices. Get delivery acknowledgement. Follow the buyer's invoice-submission system. Keep the PO and correspondence. A legal right is much easier to use when the commercial record is clean.
Delivery planning starts before production
A corporate delivery date should not be the date the founder hopes production will finish. Work backward:
Required delivery date → transport buffer → packing → quality check → production → raw-material arrival → artwork approval
If the buyer needs 500 units in Bengaluru on September 10, “dispatching on September 10” is not on-time delivery. For multi-location orders, create a dispatch sheet containing recipient/location, quantity, carton count, tracking reference and delivery status.
For larger jobs, also agree beforehand whether partial delivery is acceptable. Never solve a capacity problem by silently splitting an order the client expected to receive together.
Run a capacity test before saying yes
A useful readiness calculation is:
Normal daily capacity × realistic working days = available production capacity
Then reduce it for existing orders, rejected pieces, customization and unexpected delays. If normal output is 60 units a day, a five-day window does not automatically mean the business can safely promise 300 additional customized units. Corporate buyers generally care more about a realistic commitment delivered correctly than an impressive promise followed by excuses.
Your corporate-order readiness check
Before actively pitching larger buyers, make sure you can answer these questions in under ten minutes:
1. What is your profitable bulk price?
2. What is your standard and customized MOQ?
3. How many units can you reliably produce each week?
4. What customization can you offer without disrupting production?
5. Is your GST position clear?
6. Which registrations or licences apply to the product?
7. How much working capital would a large order require?
8. What credit period can the business survive?
9. How will bulk orders be packed and transported?
10. Who owns the order from PO to payment collection?
If several answers are still “we'll figure it out once we get the order,” the business is not yet ready to sell aggressively to corporates. That is fixable.
Frequently Asked Questions
Is GST compulsory for corporate orders? Not simply because the customer is a corporate. GST liability follows the applicable law, although individual companies may have their own vendor-onboarding requirements.
What is a good MOQ for corporate gifting? There is no universal MOQ. It should reflect production batches, customization setup, packaging minimums and the economics of fulfilling the order.
Should a small business give corporate clients credit? Only after understanding the buyer, approved terms and the cash needed to fund the order until collection. Credit is a commercial decision, not a requirement for appearing professional.
What documents do corporate buyers usually ask small suppliers for? Requirements vary, but common onboarding information can include PAN/entity details, bank details, GST where applicable, Udyam where relevant and category-specific licences.
Conclusion
Corporate selling begins long before the first corporate order. It begins when pricing can survive a bulk discount, packaging can survive transport, documentation can pass procurement, production can meet a real deadline and cash can survive the gap between making the order and being paid for it.
For small women-led brands, that operational readiness matters because discovery opportunities are growing. The strongest position is not simply, “We would love a large order.” It is: “We know exactly how we will deliver it.”